0.8%To entry--Typical win42.2%Won
ICHRLong
$2.1B capVol 17th percentileRSI 43Semiconductors
A falling wedge has two downward-sloping boundaries that draw closer together. Learn why traders watch its upper boundary, how the trade works and how to assess its historical results.
A falling wedge is a declining price range that narrows over time. Both its highs and lows fall, but the line across the highs falls more steeply than the line under the lows. The two boundaries converge.
Imagine a stock’s daily swings narrowing from a $6 range to a $3 range as it moves lower. This illustrative change makes the wedge easier to see. It describes a smaller range during the decline, while the direction of the next break remains uncertain.
A wedge can form during a pullback in a longer rally or during an extended decline. Use the trend line basics guide to review how its boundaries are drawn.
Use these features to check the shape:
Compare the slopes before naming the pattern. Roughly parallel falling lines form a channel. In a wedge, the distance between the lines decreases.
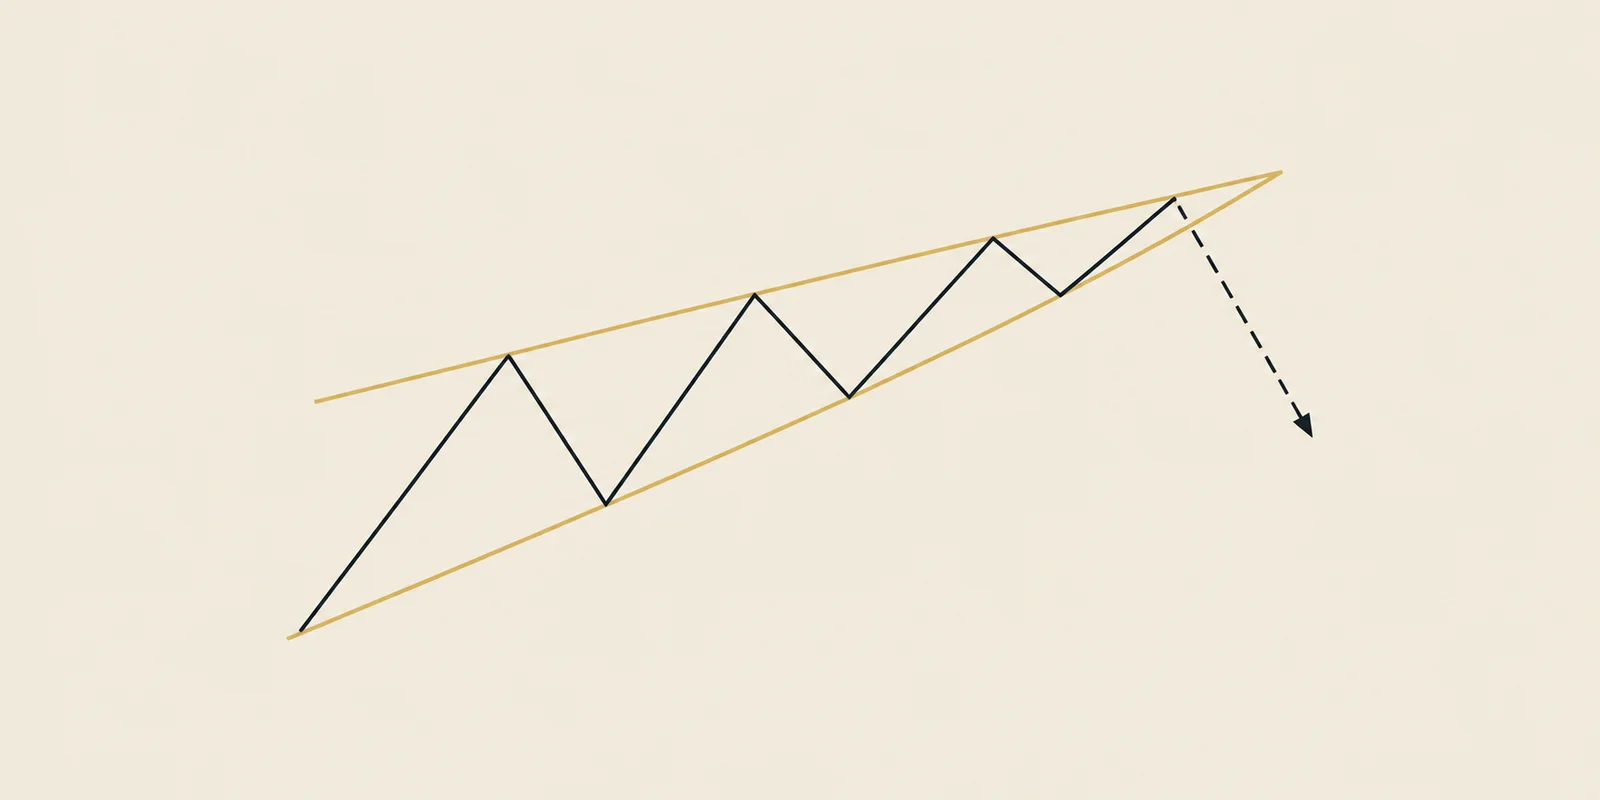
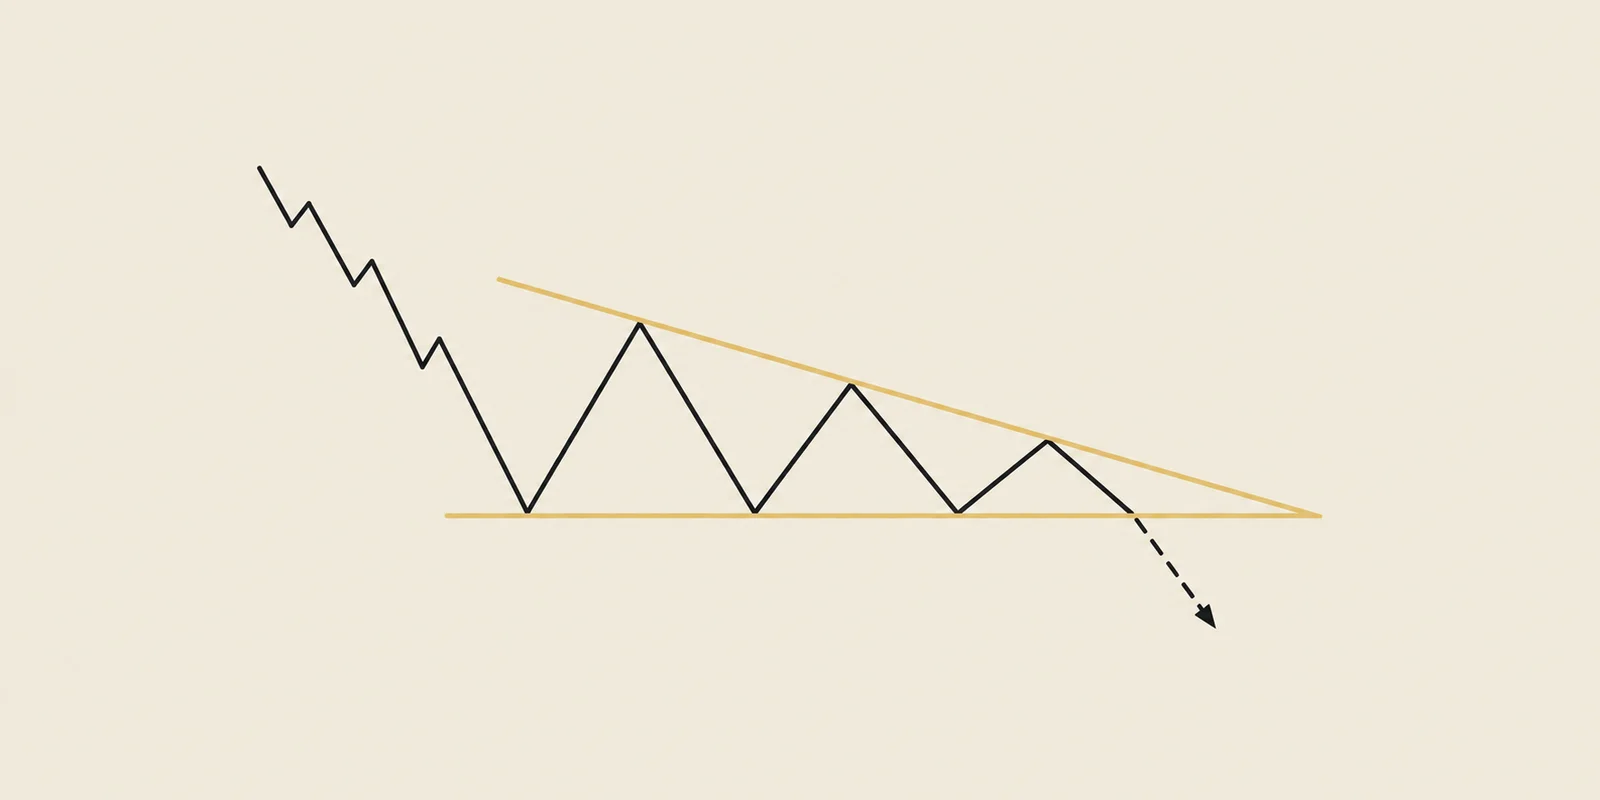
Compare the boundaries and the move preceding the consolidation to distinguish these related patterns.
Illustrative shapes. Compare the move before the pause and the direction of the two boundaries.
Traders watch a falling wedge for an upward break because the declining range is narrowing. The bullish entry starts only when price reaches the trigger beyond the upper line.
If price continues lower through the wedge, the proposed upward breakout has not occurred. If it breaks upward and then reverses, the position follows the safety-exit rule described below.
The following steps describe TradingPal’s historical simulation. Choose each step on the diagram to see where the price level sits. The risk/reward guide explains how the distance from entry to the safety exit becomes the planned risk, or 1R.
The simulation places its entry trigger above the upper boundary. The pattern must have been established on an earlier daily candle. The first eligible candle to reach the trigger can fill the order. If price gaps past it overnight, the simulation uses the worse opening price.
The planned invalidation level sits below the last low before the breakout. The test closes the trade at the close of a later daily candle beyond that level. Price can overshoot it or gap past it, so the actual loss can exceed the planned 1R.
Measure the pattern’s height at its widest point and project that distance from the entry trigger in the direction of the trade. This is the measured-move target. Reaching the upside target activates a trailing exit based on the 10-day moving average, the average of the last ten daily closing prices. The trade ends on a later close below that average.
A pattern can look convincing and still disappoint as a trade. We tested two familiar trading ideas to see whether they actually helped. Here is what we found in those historical simulations.
Put two falling wedges side by side. One squeezes into a neat, narrow shape. The other looks wider and less convincing. It is tempting to trade only the cleaner-looking one.
We tested that idea by taking 1,149 past setups and removing the 264 looser wedges. Being pickier made the simulated account earn less: its annual return fell from 14.5% to 10.7%, measured as the yearly rate that would produce the same total return over the test.

Giving up those trades did little to soften the worst fall. Both accounts still suffered a drop of about 27% from their previous high. We also tried 25 different orders for choosing trades when the account could not take them all; removing the loose wedges hurt returns every time.
Those runs use the same history, so this does not mean every loose wedge is worth buying. It means this particular filter threw away useful trades without doing much to soften the worst fall. A cleaner drawing alone was not a good reason to reject a setup.
Read the full study: Does a tighter falling wedge make a better trade? →Your trade reaches its target, then starts giving back the gains. When the exit signal arrives, you think: “I will give it a little longer to recover.”
We tested that choice. Our usual rule lets a trade run after its target until price closes below its ten-day average. The alternative ignored that exit if price had also fallen below the original target. Holding longer improved the average falling-wedge trade—but that was only part of the story.

In a separate simulated account trading several patterns, holding longer made the overall result worse. Annual return fell from 20.12% to 12.52%, while the biggest drop from an account high grew from 16.4% to 30.4%. A trade can recover eventually while tying up money or giving back gains along the way. That is why a better average trade does not necessarily make a better account.
These account numbers cover several patterns, not just falling wedges. The older report retains its results, but we could not recover the original trade-by-trade records to fully recheck the comparison.
Read the full study: Can holding through a pullback hurt the whole account? →The table summarizes simulated trades using the entry and exit rules above. Check the direction, sample size and measurement period before comparing rows. These results update when a new historical run is published.
Read win rate together with the size of the wins and losses. A strategy can win half its trades and still gain or lose overall. Average R and profit factor help explain which happened; the track-record metrics guide covers the calculation.
The published pattern group includes shapes that passed later confirmation checks. That can affect which historical trades enter the sample, even when the simulated fill uses prices available at the time. The backtesting methodology explains this limitation and the portfolio assumptions.
Historical results of the simulated strategy described above (2006-10-13 – 2026-09-09), refreshed nightly — not a prediction. How we test →
The examples below are selected completed trades from the historical simulation. Compare the entry and exit in each, including the losing trades. Opening a symbol takes you to its current chart.
Selected for learning, with a mix of wins and losses where available. Closed in the 90 days ending Sep 11, 2026. This selection is not a win-rate sample.
Our screener re-draws these lines on 2,600+ symbols every night and flags each chart that fits the checklist above. The current matches appear below.
60 fresh falling wedges formed in the last 45 days across our growing universe of 2,600+ scanned symbols (75 charts tracked for this pattern in total). Scan updated Sep 11, 2026.
60 structures found. See example
The day's #1 ranked setup, in your inbox.
Every morning we hand you the highest-ranked breakout structure found in our scan across 2,600+ tickers — Free.
See the full offeringIt is commonly watched for an upward break. The tested bullish position starts at the upward trigger and has a defined safety exit if the move reverses.
Price must reach the trigger beyond the upper boundary after the pattern could be established on an earlier daily candle. A visible wedge alone does not start the simulated trade.
Project its widest height upward from the entry trigger. After that target is reached, the tested bullish policy exits on a later close below the 10-day moving average.
A bull flag has roughly parallel boundaries and follows a sharp rally. A falling wedge has converging boundaries and does not require a preceding rally.
Use the historical results for the stated entry and exit rules. Win rate, average R, profit factor and sample size together describe those trades more fully than a single percentage.
A rising wedge has two upward-sloping boundaries that draw closer together.
A descending triangle combines repeated lows near one price with falling highs.
A bullish pennant forms when a sharp rally pauses in a small, narrowing range.
Educational content, not investment advice. Backtest statistics are historical results of a simulated strategy, refreshed nightly — they describe the past, not the next trade.